Article
Direct Lending: Attractive Economics in a Shifting Environment
A reset in interest rate expectations and widening of credit spreads have shifted the direct lending dynamics for investors. In turn, we believe private credit has become increasingly attractive over the course of this year.
Multiple Drivers of Yield Enhancement
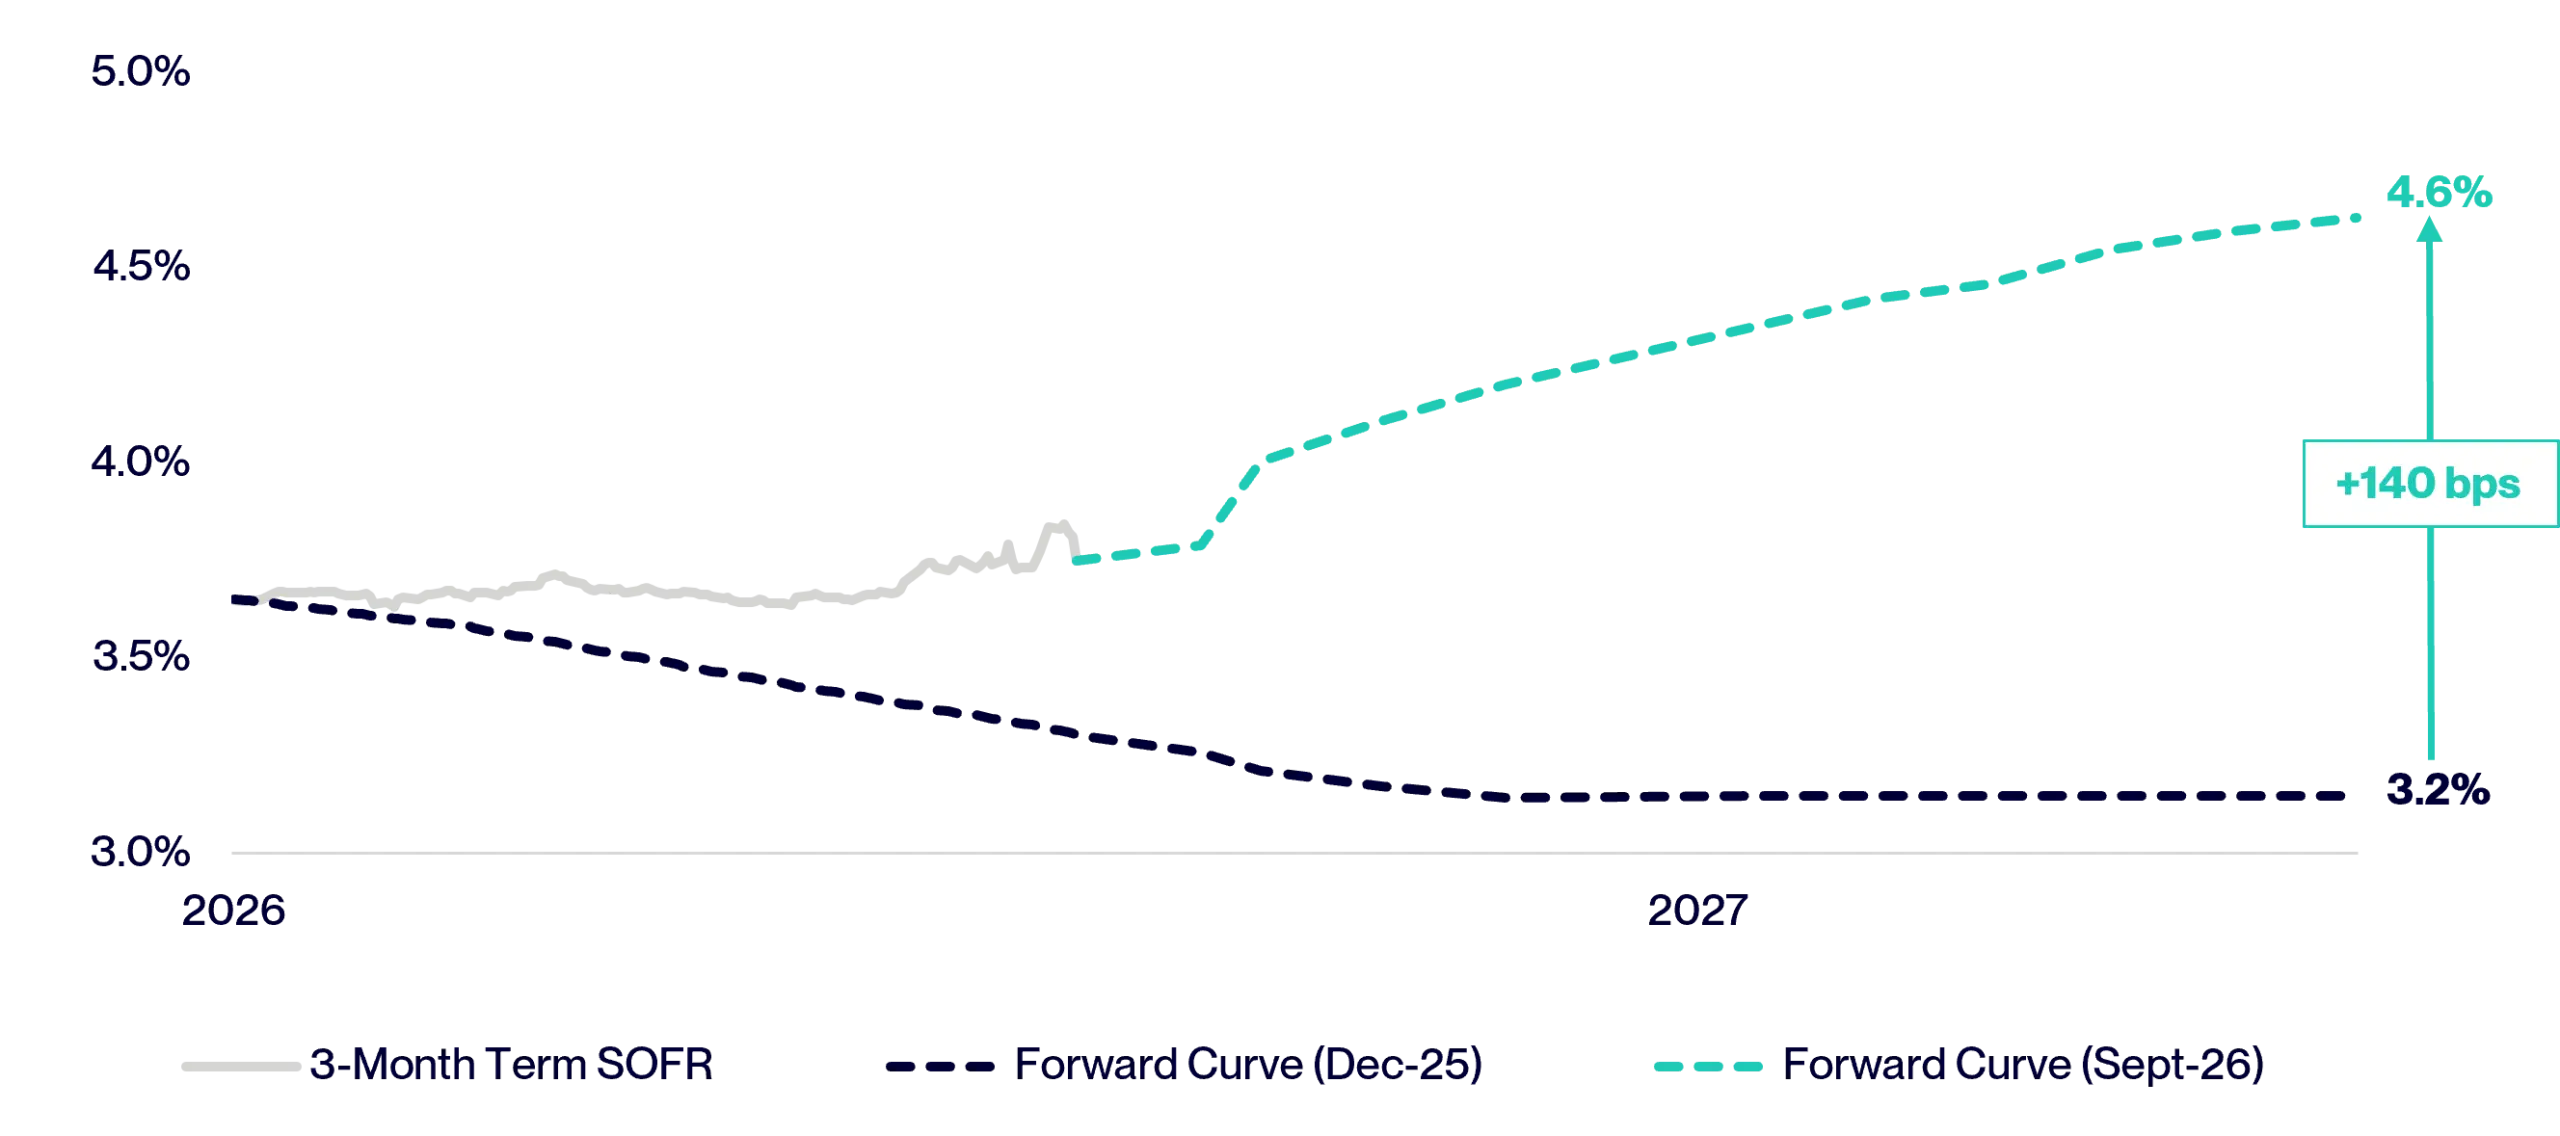
At the start of 2026, market participants broadly anticipated multiple interest rate cuts, and the forward curve would suggest a SOFR level of approximately 3.2% in the second quarter of 2027.1 However, persistent inflation and a more resilient economic backdrop have materially altered the outlook, with forward markets now implying that rates could rise north of 4.6% by mid-2027.1 As a result, private credit strategies, which typically feature floating rate structures, are well-positioned to benefit from a prolonged ‘higher-for-longer’ rate environment.
SOFR Base Rates and Forward Curve1
Importantly, the improvement in yield expectations is not solely a function of higher interest rates. Credit spreads have also widened as lenders have become more selective amid elevated market uncertainty.2 While dry powder remains relatively accessible, we believe underwriting standards have tightened, and lenders are demanding greater compensation for risk, resulting in more attractive economics on newly originated transactions. In our view, the combination of higher base rates and wider spreads has meaningfully enhanced prospective yields across the asset class.
New Investments in Focus
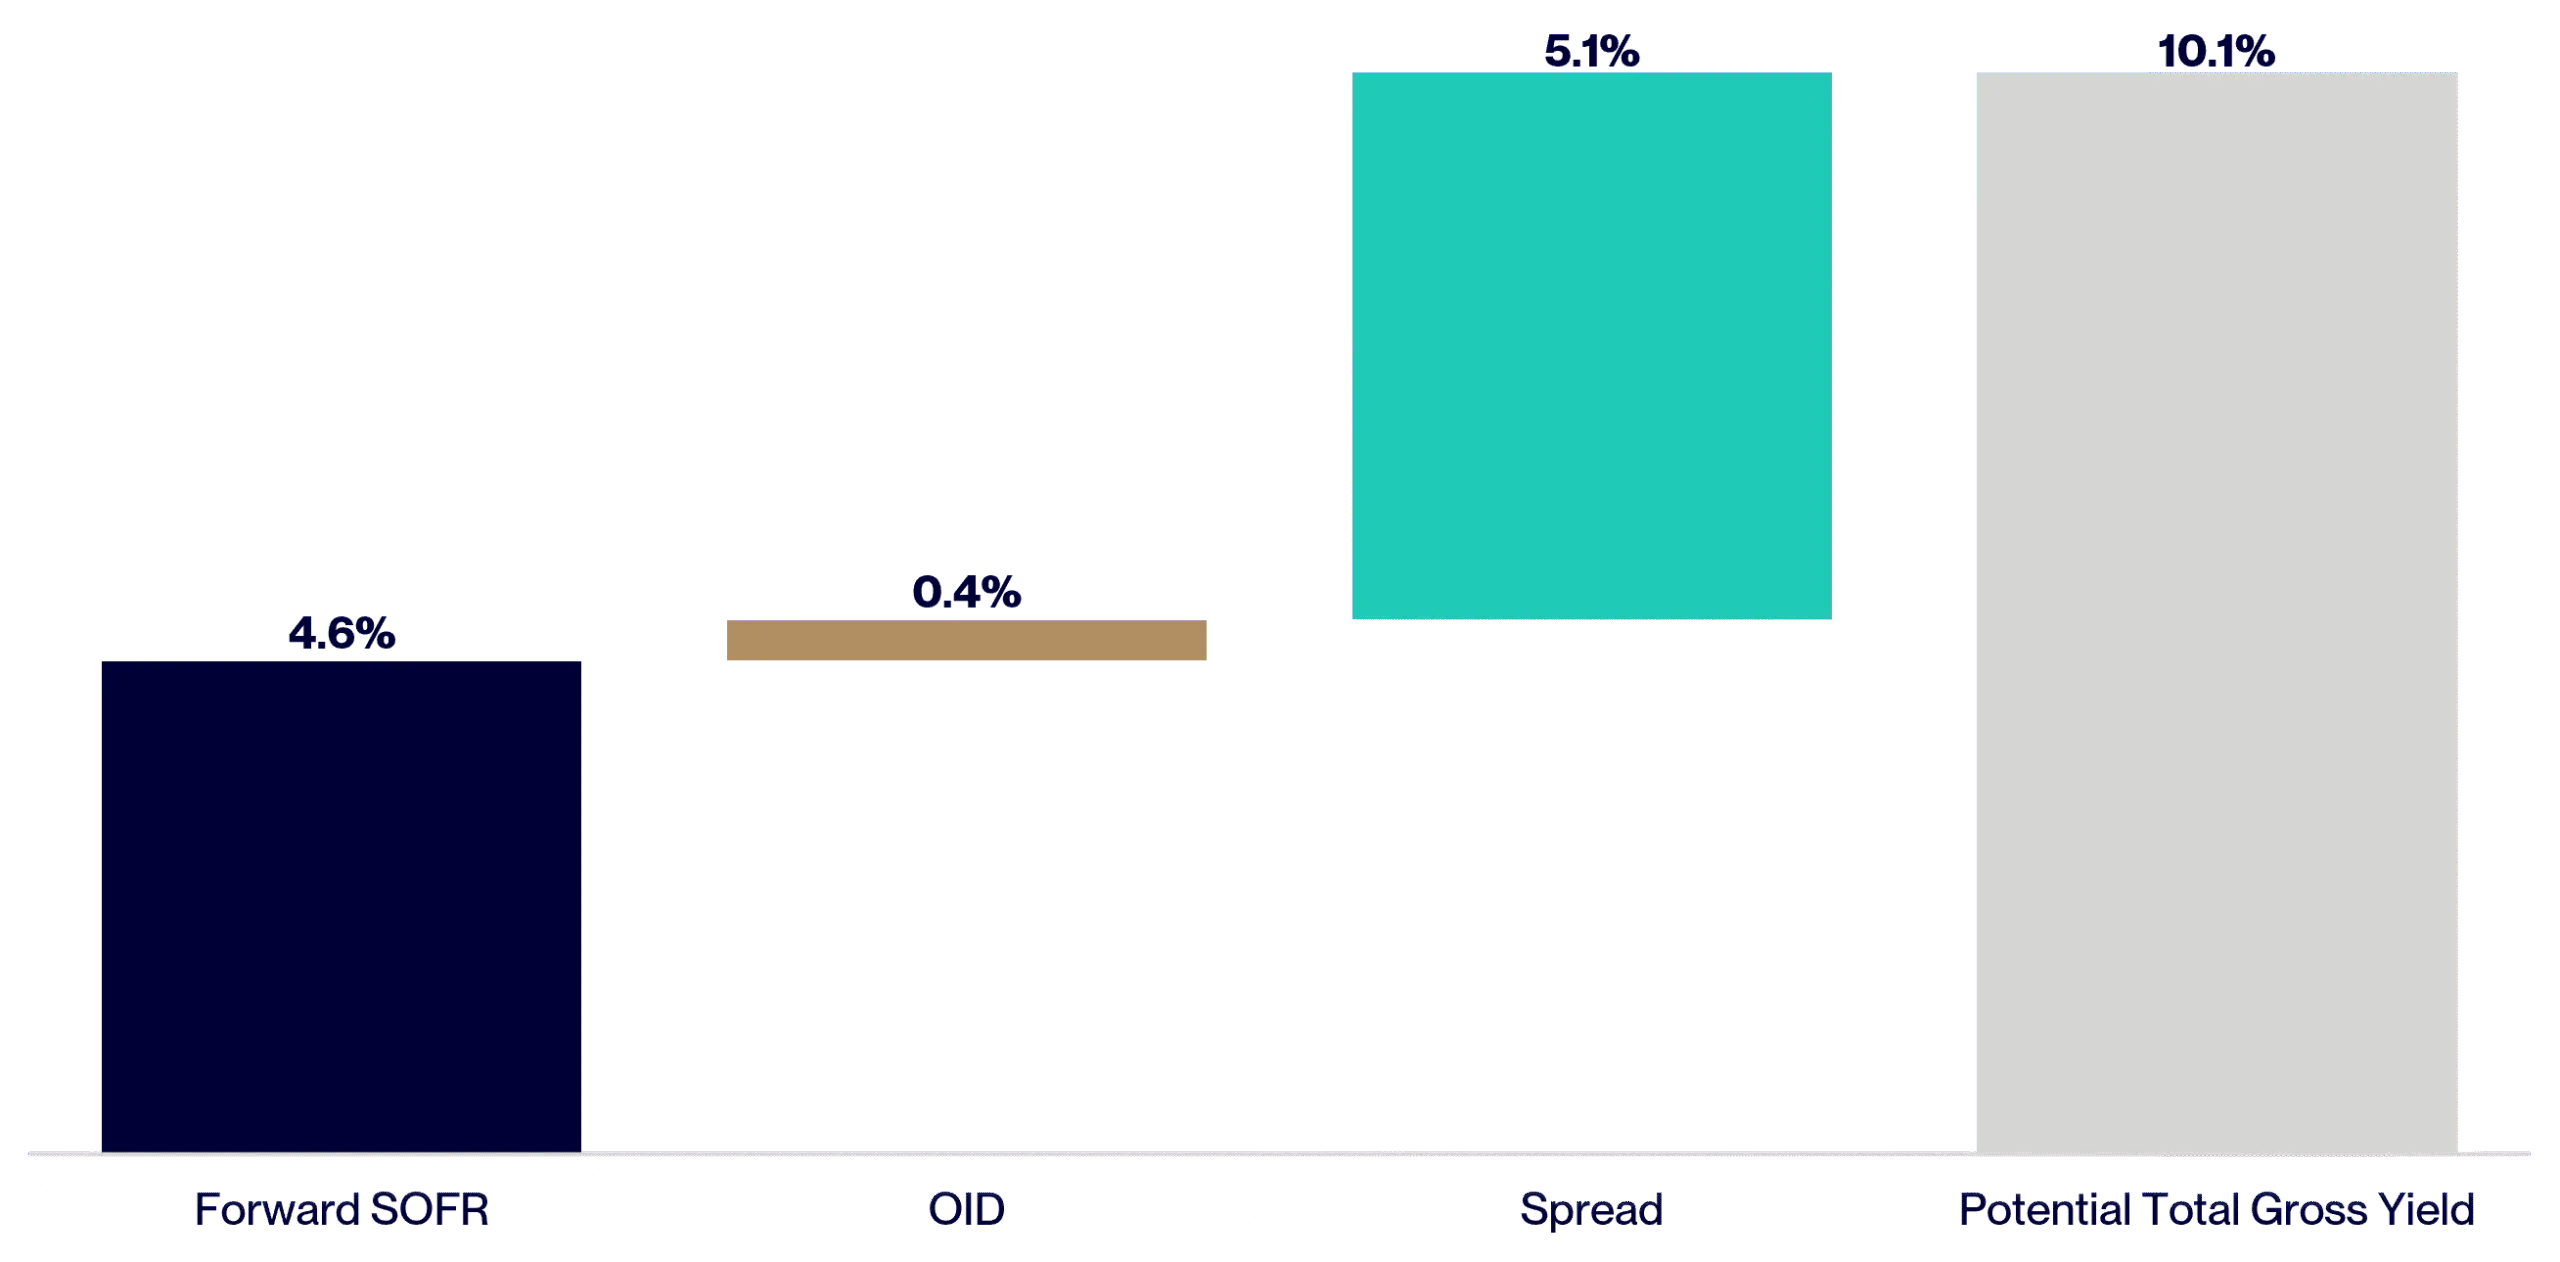
These dynamics have driven a significant increase in expected returns for new investments. Gross asset yield expectations have risen from approximately 8.5% at the beginning of the year to ~10% today, representing one of the most meaningful improvements in direct lending economics in recent years.1,3 For investors seeking income-oriented strategies, we believe the current market offers an attractive opportunity to deploy capital at yields that are substantially higher than those available just months ago while maintaining exposure to senior, floating-rate assets.
Potential All-In Gross Yield1,3,4
The current backdrop is especially compelling, in our view, because the potential for enhanced yield can still be achieved while maintaining disciplined underwriting standards. In our view, heightened uncertainty has encouraged private credit managers to focus on resilient businesses, conservative capital structures, and enhanced lender protections. As a result, many newly originated transactions are offering higher yields alongside improved documentation, tighter covenant packages, and greater downside protection than was available during the more competitive lending environment of recent years.3
Furthermore, we believe this represents a particularly attractive environment because improved gross yield potential is being driven by stronger market fundamentals rather than increased risk-taking. Borrowers continue to place significant value on the speed, certainty, and flexibility of private capital that is often unavailable in public markets, enabling lenders to maintain disciplined underwriting standards while capturing higher yields and enhanced downside protections.
Larger Companies Continue to Remain Attractive
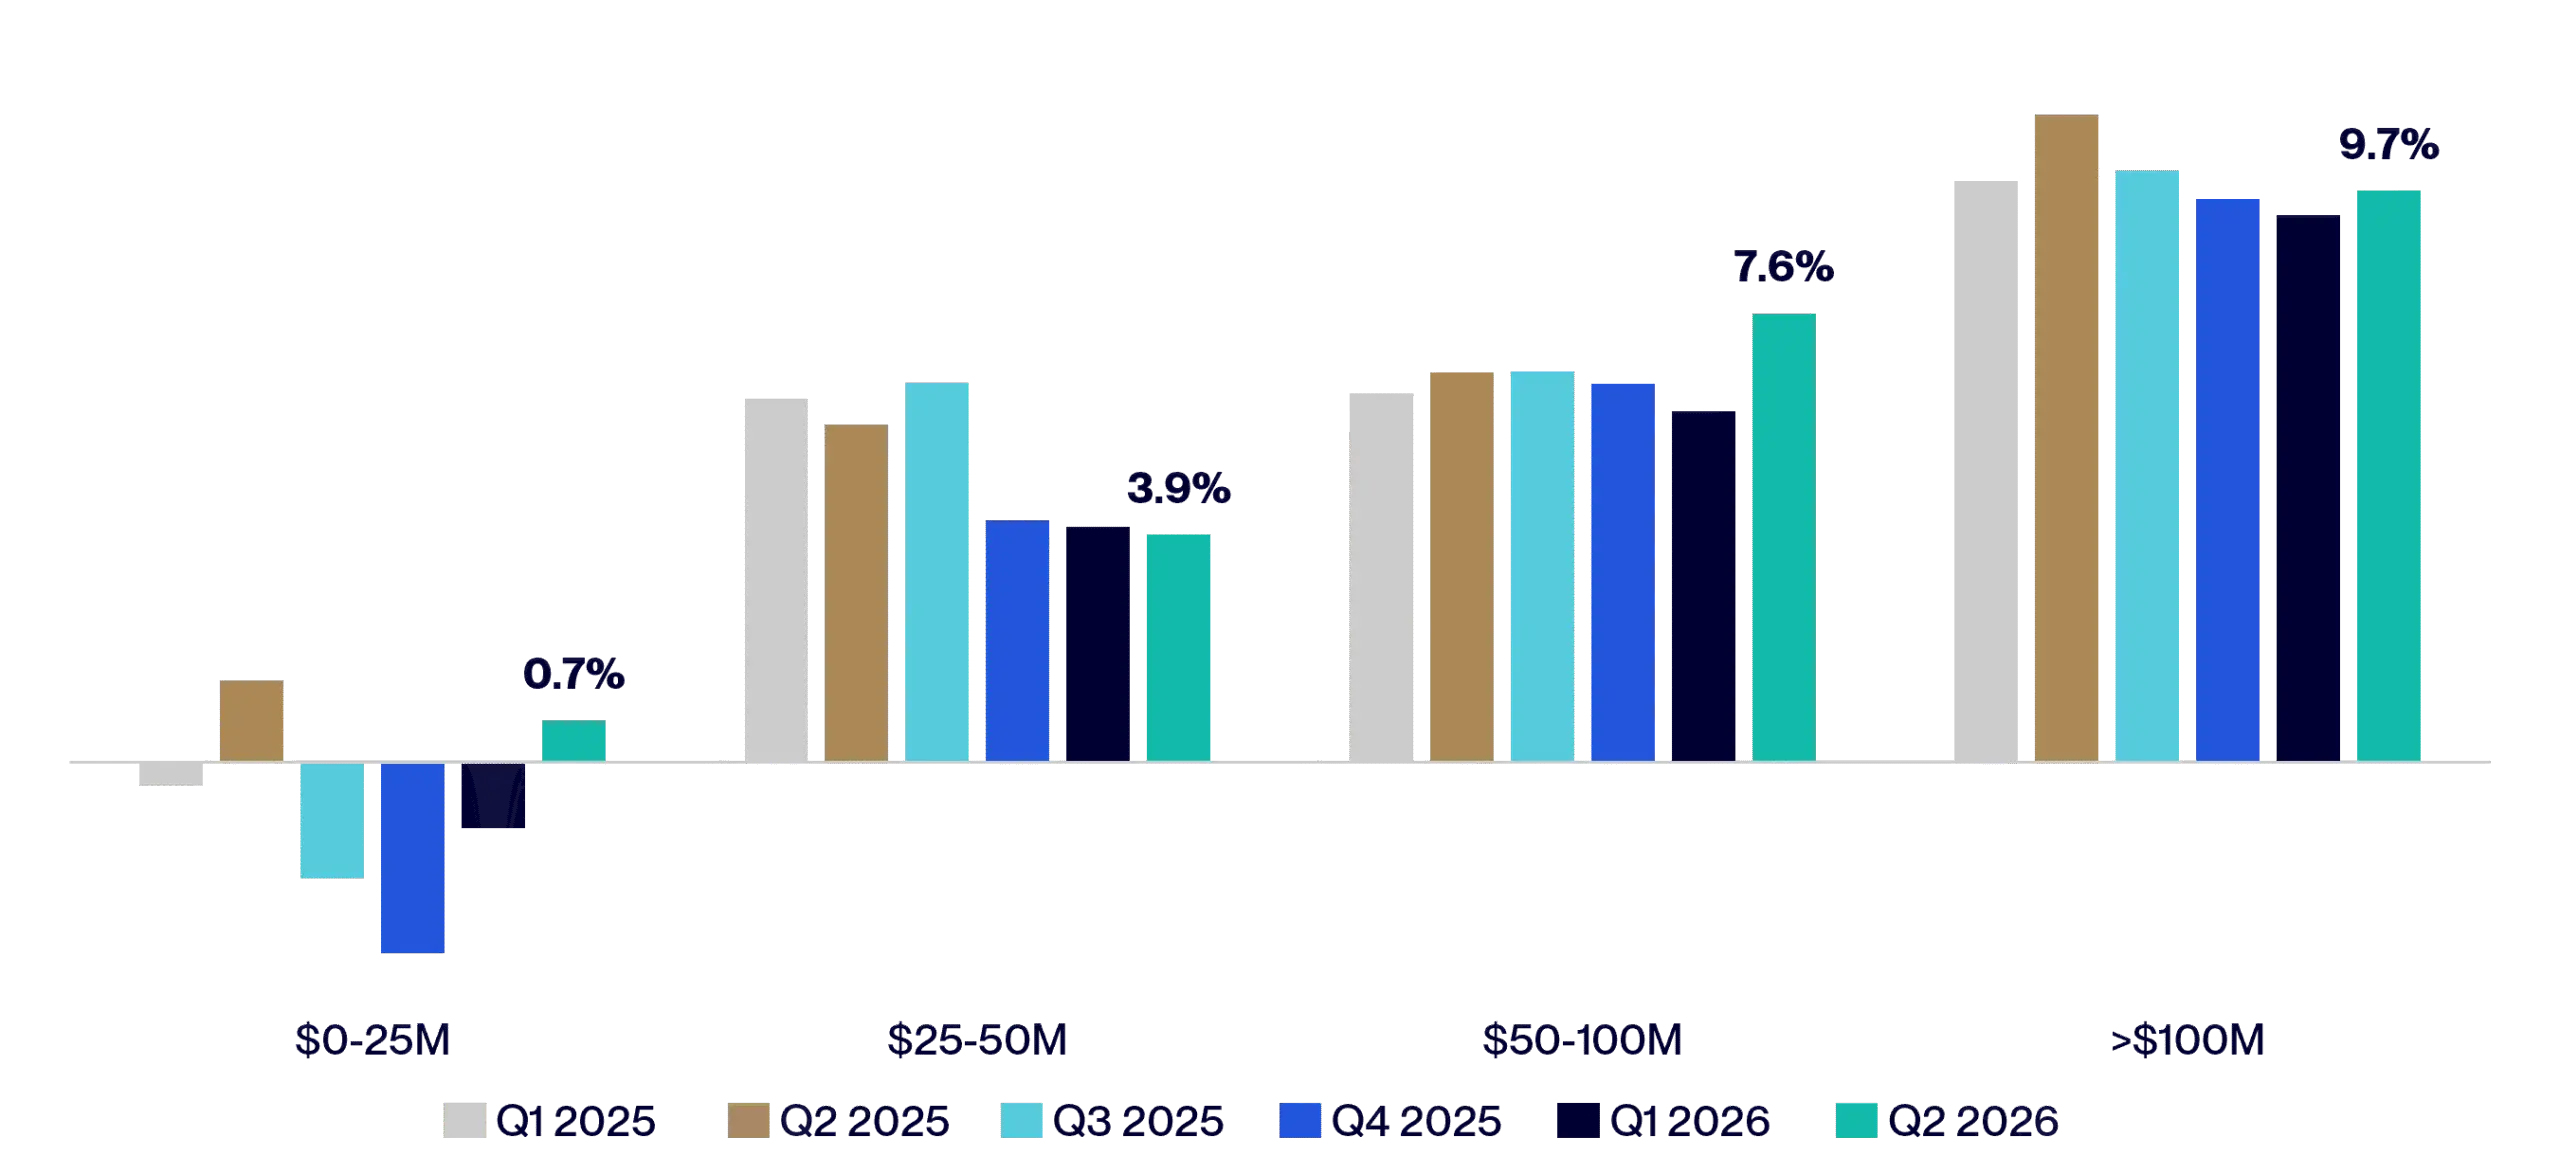
Borrower fundamentals, particularly for larger, well-established companies, continue to remain resilient.5 Bigger businesses often benefit from diversified business models, strong free cash flow generation, and enhanced financial flexibility, which can help them to better navigate higher interest rate and uncertain macroeconomic environments than smaller issuers. In our view, this has created favorable market conditions for private credit managers focused on upper-middle-market businesses, where credit performance has been resilient.5
Year-Over-Year Last Twelve Months’ EBITDA Growth by Company Size (Based on EBITDA)5
Record Institutional Fundraising
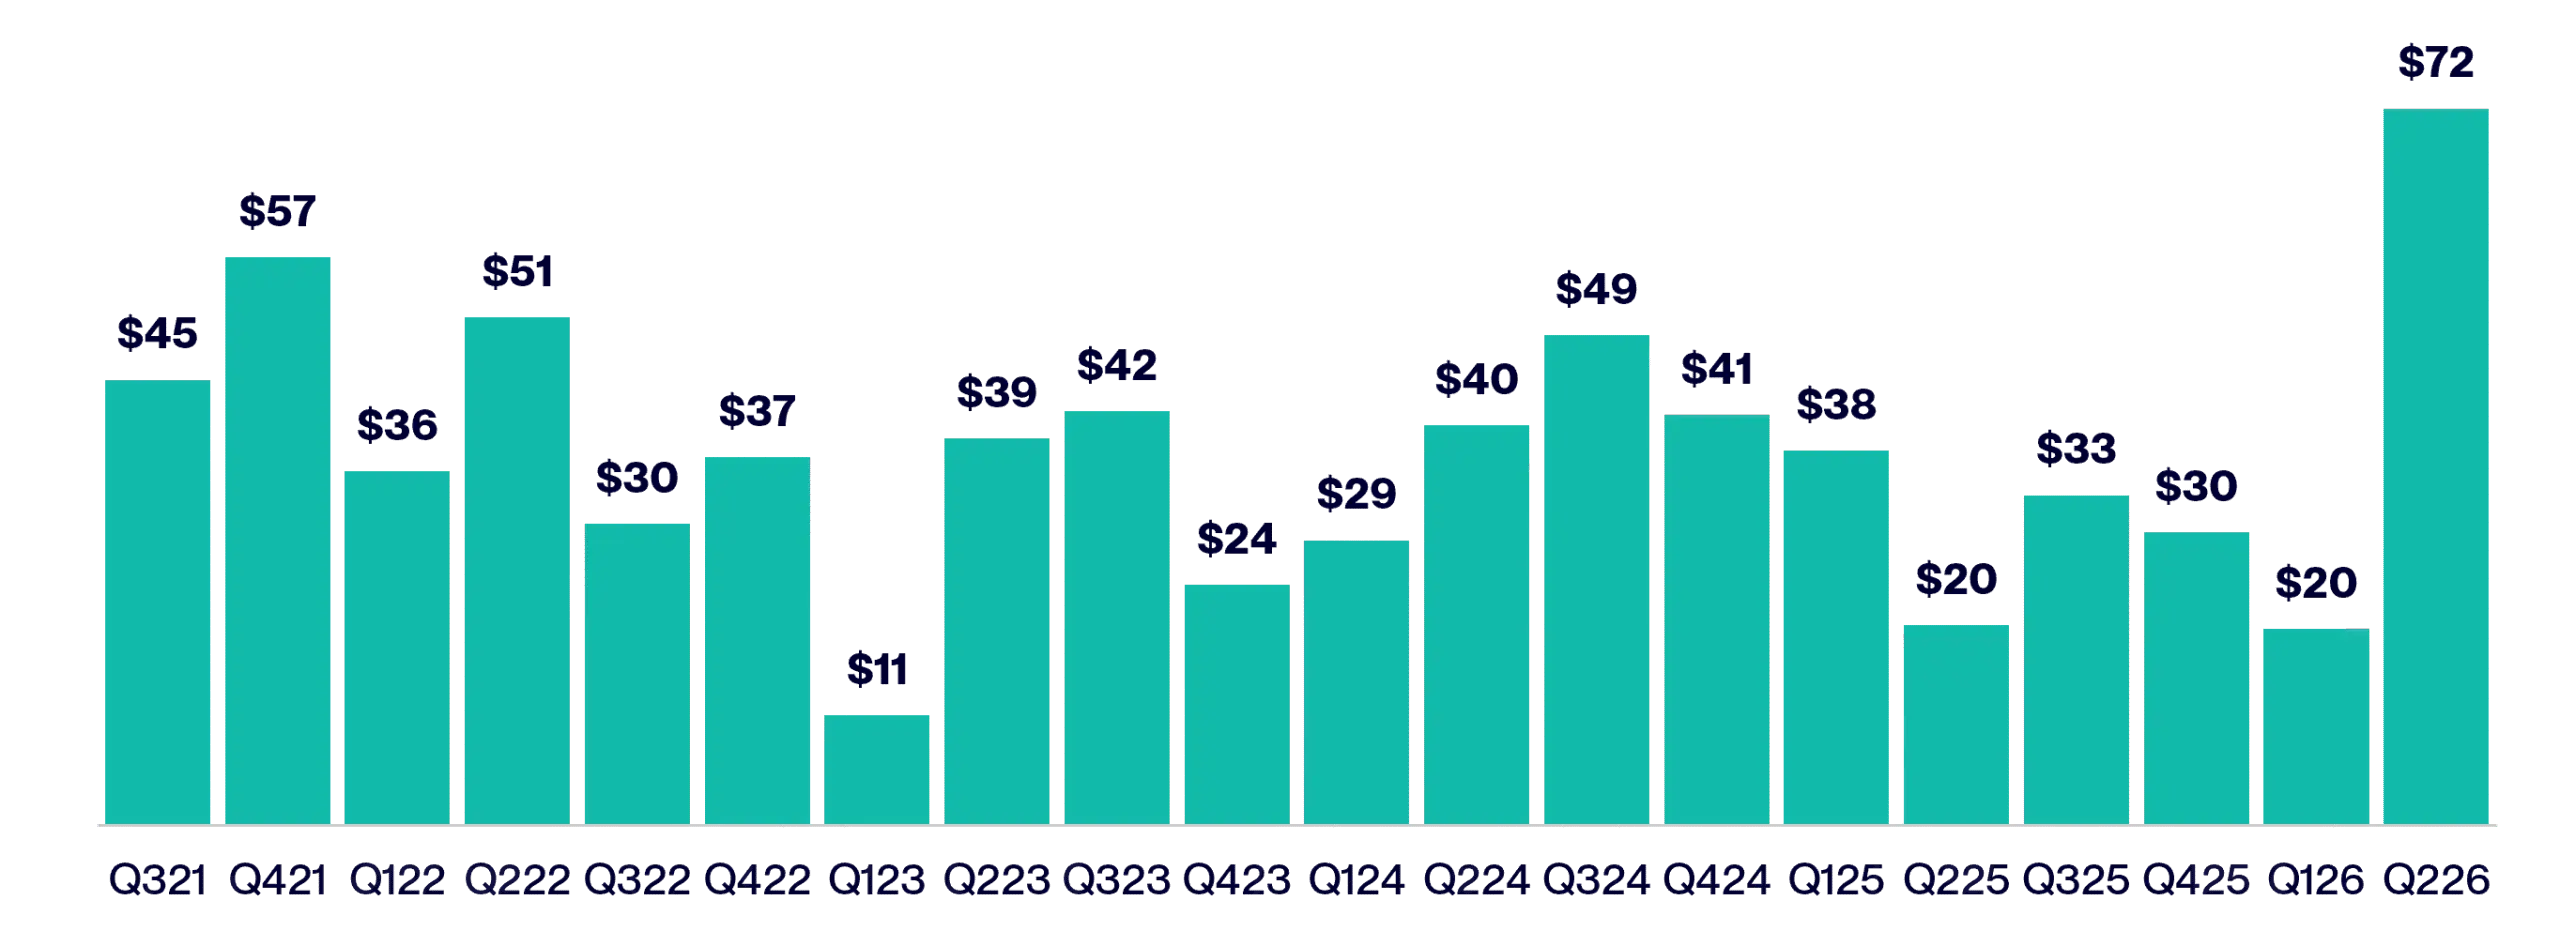
Institutional investors appear to be increasingly recognizing the attractiveness of the private credit opportunity set. According to Preqin, direct lending drawdown funds raised a record $72 billion in the second quarter of 2026, underscoring what we believe to be continued institutional conviction in both the durability and long-term value of the asset class. In contrast, repurchase requests across ten of the largest non-traded BDCs reached an average of 9.9% of shares in the second quarter following a sharp increase over the prior three quarters.6 In our view, this divergence highlights a distinction between institutional investors, who remain focused on the asset class’s underlying fundamentals and improving return profile, and portions of the wealth channel, where flows have been more heavily influenced by short-term market headlines.
Aggregate Fundraising for Direct Lending Funds6
Conclusion
While market conditions will inevitably evolve, we believe today’s environment highlights the value of disciplined capital deployment and rigorous credit selection. Taken together, the current combination of enhanced income potential, resilient borrower fundamentals, and sustained institutional demand supports a highly constructive outlook for direct lending and what we believe is one of the most attractive vintage opportunities in recent years.
End Notes
1 Source: Bloomberg. SOFR = CME Term SOFR 3 Month. Forward curve forecasts as of December 31, 2025 and September 15, 2026, as applicable.
2 Based on HPS market observations.
3 Source: KBRA DLD as of June 30, 2026. Spread does not reflect the return of direct lending funds, which will be reduced by, among other things, fees and expenses, or the return that may ultimately be realized on an investment. Higher spreads may represent higher cost of capital for borrowers, and such costs may increase the risk of default or the risk that the loan may otherwise become impaired. Source: KBRA DLD as of June 30, 2026. OID of 1.15% is amortized over a three-year horizon.
4 Potential total gross yield reflects the sum of (i) forward SOFR expectations for mid-2027 (determined as of September 15, 2026), (ii) direct lending OID information as of June 30,2026 and (iii) direct lending spread information as of June 2026. The information provided herein is included to show the general trend in the applicable markets in the periods indicated and is not intended to imply that the yields herein are achievable or guaranteed. Actual yields earned over the life of an investment could differ materially from the potential yields presented above. Higher yields represent higher cost of capital for borrowers and such costs may increase the risk of default or the risk that the loan may otherwise become impaired. Potential yield does not reflect the return of any fund, which will be reduced by, among other things, fees and expenses, or the return that may ultimately be realized on this investment.
5 Source: Lincoln VOG Proprietary Private Market Database © 2026 Lincoln Partners Advisors LLC. All rights reserved. Use of these materials without Lincoln’s consent is prohibited. Includes data from the database through the second quarter of 2026.
6 Source: Preqin as of June 30, 2026. Fundraising figures include closed end direct lending funds.
Important Disclosures
PAST PERFORMANCE IS NOT NECESSARILY INDICATIVE OF FUTURE RESULTS. The data and information in this material, which has been prepared by HPS Investment Partners, LLC (“HPS”), are presented for informational purposes only. All charts, graphs and images are shown for illustrative purposes only. This material does not constitute an offer to sell or the solicitation of any offer to buy any interest, security, including any interests in any HPS managed funds or accounts, which offer can only be made by definitive offering documentation, which will contain material information with respect to any such interest or security, including risk factors relating to any such investment. All information provided herein is as of the date set forth on the cover page (unless otherwise specified) and is subject to modification, change or supplement in the sole discretion of HPS without notice to you. While this document expresses views as to certain investment opportunities and asset classes, HPS may undertake investment activities on behalf of one or more investment mandates inconsistent with such views subject to the requirements and objectives of the particular mandate. The investments and asset classes mentioned in this document can be highly illiquid, are speculative and may not be suitable for all investors. This document does not provide tailored investment advice and is primarily intended for distribution to institutional investors (as defined under (FINRA Rule 2210(a)(4)). Investing in such investments is only intended for experienced and sophisticated investors who are willing to bear the high economic risks associated with such an investment. Investors should carefully review and consider potential risks as well as their specific investment objectives and experience, time horizon, risk tolerance, and financial situation before making any investment decisions. Nothing contained in these materials constitutes investment, legal, tax or other advice nor is it to be relied on in making an investment or other decision. HPS makes no representation or warranty (express or implied) with respect to the information contained herein (including, without limitation, information obtained from third parties) and expressly disclaims any and all liability based on or relating to the information contained in, or errors or omissions (negligent or otherwise) from, these materials; or based on or relating to the recipient’s use (or the use by any of its affiliates or representatives) of these materials. This document may contain “forward-looking” statements. These are based upon a number of assumptions concerning future conditions that ultimately may prove to be inaccurate. Such forward-looking statements are subject to risks and uncertainties and may be affected by various factors that may cause actual results to differ materially from those in the forward-looking statements. Any forward-looking statements speak only as of the date they are made, and HPS assumes no duty to, and does not undertake to, update forward-looking statements or any other information contained herein. The success or achievement of various results and objectives is dependent upon a multitude of factors, many of which are beyond the control of HPS. The document may not be copied, reproduced, republished, posted, transmitted, distributed, disseminated, disclosed, quoted, or referenced, in whole or in part, to any other person without HPS’s prior written consent. Certain information contained herein, including indices and economic trends is, is based on or is derived from information provided by independent third-party sources. HPS believes that such information is accurate and that the sources from which it has been obtained are reliable; however, it cannot guarantee the accuracy of such information and has not independently verified the accuracy or completeness of such information or the assumptions on which such information is based. Any index information provided herein is included to show the general trend in the applicable markets in the periods indicated and is not intended to imply that the any investment product is similar to any index in composition or element of risk. The indices are not available for actual investment. No index is directly comparable to the investment strategy of any investment product. Moreover, independent third-party sources cited in these materials are not making any representations or warranties and do not guarantee the accuracy, completeness or availability of any information attributed to them and shall have no liability in connection with the use of such information in these materials, including for any errors or omissions (negligent or otherwise), regardless of the cause, or for the results obtained from the use of such content.
General/Loss of capital: An investment in the asset class or in investment vehicles that invest in the asset class described herein involves a high degree of risk. There can be no assurance that investors’ return objectives will be realized, and investors could lose up to the full amount of their invested capital. Limited liquidity: An investment in investment vehicles that invest in the asset class described herein may provide limited liquidity and interests in such vehicles may not be freely transferable or redeemable. There may be no secondary market for interests in such vehicles. Dependence on Manager: The manager of any investment vehicle that invests in the asset class described herein may have total trading authority over such vehicle. Decisions made by such manager may cause investors to incur losses or to miss profit opportunities on which they would otherwise have capitalized. Volatility: Investment techniques used by an investment vehicle that invests in the asset class described herein may include the use of leverage and derivative instruments such as futures, options and short sales, which amplify the possibilities for both profits and losses and may add volatility to such vehicle’s performance. Regulation: An investment vehicle that invests in the asset class described herein may not register as an investment company under the U.S. Investment Company Act of 1940 or similar laws or regulations. Accordingly, the provisions of such laws and regulations would not be applicable.
The foregoing risk factors do not purport to be a complete explanation of the risks involved in an investment in the asset class, or in investment vehicles that invest in the asset class, described herein. Investors in any security should read the entire offering materials of such security before making investment determinations.
Where applicable, this material has been distributed by HPS Securities LLC (“HPS Securities”), an affiliate of HPS and a broker/dealer registered with the U.S. Securities and Exchange Commission and member of the Financial Industry Regulatory Authority (“FINRA”) and the Securities Investor Protection Corporation (www.sipc.org). HPS Securities does not provide research reports.